Moving insurance helps protect household goods from certain loss or damage during a move in Youngstown. It may come from a mover’s valuation option or a separate policy. The move type, packing service, item value, exclusions, and claim rules all affect what a customer may recover.
A move can feel complete when the last box enters the new home. A cracked mirror, missing lamp, or damaged table can change that quickly. Knowing the terms before moving day gives you a clear plan and fewer surprises.
Moving insurance is a common name for several forms of protection. A mover may offer valuation coverage, while an insurance company may sell a separate policy. These choices work in different ways, so review the moving estimate and service agreement with care.
Table of Contents
- What does moving insurance actually cover?
- What types of damage does moving insurance cover?
- What is released value protection, and how does it work?
- What is full-value protection for a household move?
- Does moving insurance cover items I pack myself?
- How do you file a moving insurance claim?
- How can you choose the right protection for your move?
- Frequently Asked Questions
- Conclusion
What does moving insurance actually cover?
Moving insurance may cover household goods that are lost or damaged during a move. The exact protection depends on the written valuation option, service agreement, and cause of the damage. Read these terms before signing or letting the crew start work.
The difference between valuation and insurance
Valuation is the mover’s stated responsibility for goods under the moving agreement. It is not always the same as an insurance policy. A separate policy may come from an insurance company and may have different limits, exclusions, claim steps, and payment rules.
People often use the phrase moving insurance for both choices. A careful customer asks which type applies. Ask who handles the claim and whether the mover, insurer, or another provider makes the final decision.
Your written moving estimate should show the protection you choose when possible. Keep a copy with the inventory, service agreement, and payment records. These papers can help if something is damaged or missing after delivery.
Why coverage depends on the move and service agreement
Protection can change based on the move type. A local home move, long-distance move, office relocation, storage move, or loading-only job may have different terms. The agreement should say what the crew does and when responsibility begins and ends.
For example, a mover may pack, load, transport, and unload your goods. Another customer may pack every box and hire loading and unloading help only. These services can change how a claim is reviewed. Youngstown Movers can help customers know which questions to ask before booking.
The agreement should also list exclusions. These may include owner-packed goods, items with old damage, fragile goods, plants, cash, or goods that were not listed correctly. The exact rules matter more than a general promise that belongings are protected.
What types of damage does moving insurance cover?
Moving insurance may cover accidental damage or loss that happens while the mover is responsible for the goods. Examples include a broken table leg, a crushed box, or an item that never arrives. Coverage is not automatic for every type of loss.
Damage caused during packing, loading, and transport
A mover may be responsible for damage caused during services listed in the agreement. This may include packing an item, carrying it through a doorway, placing it in the truck, securing it, and unloading it at the new home.
Good records make the item’s condition easier to prove. Take clear photos of valuable goods before packing. Note old marks on the inventory and photograph boxes, furniture, and appliances after delivery.
Professional movers may use blankets, wrap, cartons, straps, and other supplies. These items lower risk but cannot prevent every problem. Report visible damage before the crew leaves when possible, and keep damaged packaging.
When loss, delay, or accidental damage may be excluded
Protection may not apply when an exclusion covers the loss. Examples may include poor owner packing, normal wear, an old defect, illegal goods, or events outside the agreement. Some plans may also treat delays, storage, and weather damage in different ways.
Do not assume every problem becomes a claim. A late arrival may have a different remedy than a broken chair. Missing parts may also need a different review from a lost box.
Ask for plain-language answers before moving day. Cover owner-packed goods, high-value items, electronics, artwork, jewelry, plants, food, and goods placed in storage. Youngstown Movers can explain the services provided and help you identify questions for the written agreement.
What is released value protection, and how does it work?
Released value protection is a basic level of carrier responsibility selected in the moving agreement. It usually limits what the mover may owe for lost or damaged goods. The amount may not match the item’s full replacement cost.
How basic carrier liability is calculated
Under a released value option, the agreement may use an amount tied to the weight of an item or shipment. Ask the mover to state the calculation in writing. Payment for a damaged television, table, or box may be far below its current replacement price.
The calculation may depend on the item’s condition and how the damage happened. A claim reviewer may ask for the inventory, item details, weight information, photos, and proof of ownership. Read the agreement before guessing what the result will be.
Released value protection may suit a move with older, low-value belongings. It may not suit a home with costly furniture, work equipment, collections, or hard-to-replace items. Compare the limit with the true value of the shipment.
Why high-value belongings may need additional protection
High-value goods need special care because a basic limit may not match their worth. These items may include artwork, instruments, antiques, computers, cameras, jewelry, or custom furniture. List them and ask whether a separate declaration or appraisal is needed.
A mover may also have rules for goods you transport yourself. Those items may fall outside the mover’s responsibility once they leave the truck or crew’s control. Ask before moving the item rather than after a problem happens.
A moving company can explain its choices, but read the actual terms. Youngstown Movers serves customers who need clear answers about packing, loading, transport, and protection before work begins.
What is full-value protection for a household move?
Full-value protection is a wider valuation option. It may make the mover responsible for repairing, replacing, or paying for eligible lost or damaged goods. It does not mean every item receives unlimited payment. Limits, deductibles, exclusions, and declared values still apply.
Repair, replacement, or reimbursement options
When a covered item is damaged, the mover may choose to repair it. If repair is not suitable, the mover may replace it with a similar item or pay an amount based on the agreement. Ask how the mover chooses between these options.
Replacement does not always mean a new item with every feature. A settlement may depend on age, condition, type, and availability. You may need receipts, photos, appraisals, or other proof to support a higher value.
The inventory should describe important items clearly. “Chair” may not be enough for a custom leather chair or antique piece. Include the brand, model, material, color, condition, and visible marks.
Deductibles, limits, and coverage exceptions to review
A deductible is the amount you may pay before protection applies. A policy or valuation option may also set a total limit for the shipment or selected items. These details can change the final payment.
Review the complete list of exclusions. Ask whether the plan covers owner-packed boxes, stored goods, mechanical damage, mold, insects, weather, and items moved without crew help. Also ask whether high-value items need a separate listing.
The goal is not to choose the largest option without thought. Match protection with the shipment’s value and risk. Written details help you compare choices without relying on a quick promise.
Does moving insurance cover items I pack myself?
Items packed by the customer may have different protection from items packed by the mover. Some agreements limit responsibility for owner-packed boxes because the mover cannot see how the contents were wrapped. The exact rule depends on the agreement and selected valuation option.
How self-packed boxes affect a claim
Use strong cartons, proper padding, and clear labels. Put heavy goods in smaller boxes and light items in larger cartons. Wrap plates and bowls, place them on their edge when suitable, and cushion them so they cannot move freely.
Do not leave empty spaces around fragile goods. Towels, paper, and approved packing materials can help stop movement. A photo of the open box before sealing can show how the contents were placed.
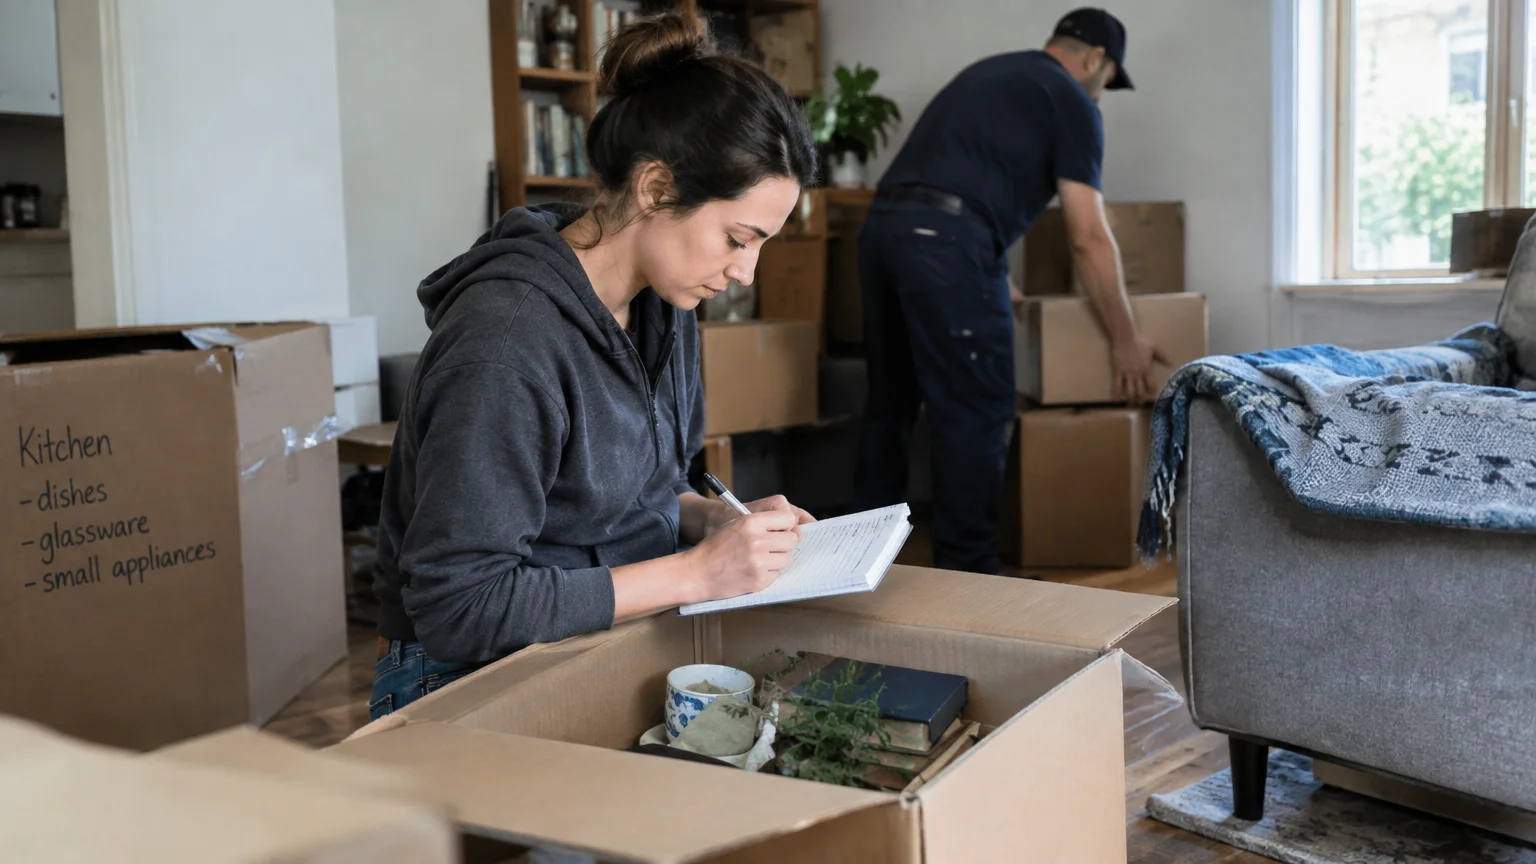
Mark boxes with the room and a short description. You may also keep a list of valuable items inside each carton. These steps do not change the agreement, but they can support a clearer claim review.
Items movers commonly exclude from liability
Movers may exclude or limit responsibility for some goods. Common examples include cash, important papers, plants, food, pets, jewelry, hazardous materials, and items you move yourself. Fragile goods packed by the owner may also have special rules.
The list is not the same for every mover or service. Request current exclusions in writing. Ask whether the crew can pack a fragile item and whether that service changes the protection terms.
For a large home or office move, professional packing can lower handling risks. Local Movers and Commercial & Office Movers may help with furniture, equipment, files, or fragile goods. Review the agreement before work starts.
How do you file a moving insurance claim?
Report damage or loss as soon as possible and follow the claim process in the agreement. Document the condition, keep damaged items and packaging, and send the requested records. Waiting can make the review harder.
What evidence should you gather before and after delivery
Before the move, photograph valuable goods from several sides. Record old marks and keep receipts or appraisals when available. A room-by-room video can also show the condition of furniture and electronics.
After delivery, inspect boxes before throwing away packaging. Photograph crushed cartons, torn wrap, broken parts, scratches, and missing items. Check the delivery inventory against what arrived.
A useful claim file may include:
- The signed moving agreement and selected valuation option.
- The inventory, delivery papers, and written damage notes.
- Photos or video from before packing and after delivery.
- Receipts, appraisals, repair estimates, or proof of ownership.
- Messages exchanged with the mover about the missing or damaged item.
Claim deadlines, inspection steps, and settlement decisions
The agreement may set a deadline for submitting a claim. Read it before the move and act soon after finding a problem. A claim may need to name each item, explain the damage, and state the remedy requested.
The mover or insurer may ask to inspect an item. Avoid repairing, discarding, or selling damaged goods before inspection unless safety requires it. If a damaged appliance is dangerous, protect people first and keep photos and service records.
A settlement may offer repair, replacement, or payment. Compare the offer with the agreement and ask questions when the decision is unclear. Clear records and calm messages can help keep the process organized.
How can you choose the right protection for your move?
The right protection depends on the shipment, selected services, value of the goods, and your comfort with risk. A small move with older furniture may need a different choice from a home with costly electronics or special items.
Questions to ask a moving company before booking
Ask who provides the protection and whether it is valuation or a separate insurance policy. Ask what happens to owner-packed boxes, high-value goods, storage items, delays, and items moved in a personal vehicle.
Also ask how a claim starts, which deadlines apply, and whether a deductible is involved. Request the terms in writing and compare them with any separate policy you may consider.
Useful questions include:
- Which protection options are available for this type of move?
- What exclusions apply to items packed by the customer?
- How are high-value items listed and handled?
- Does the selected option include a deductible or total limit?
- Who reviews a claim and what records will be needed?
- What happens if goods remain in storage after delivery?
When separate moving insurance may be worth considering
A separate policy may be worth reviewing when the shipment has valuable, fragile, unusual, or hard-to-replace items. It may also help when you want protection that differs from the mover’s valuation terms. Compare exclusions and limits, not just the policy name.
A separate policy does not replace careful packing or a written inventory. Check whether it covers the move, travel period, storage, and owner-packed items. It should also state how claims are reported and settled.
Before booking, ask Youngstown Movers about the services included in your move. Then review the written protection terms and choose an option that fits the shipment.
Key takeaways
- Moving insurance may mean valuation protection or a separate insurance policy.
- The written agreement controls limits, exclusions, deductibles, and claim steps.
- Owner-packed boxes and high-value goods may receive different treatment.
- Photos, inventories, receipts, and damaged packaging can support a claim.
- Match protection with the real value and risk of the move.
Frequently Asked Questions
Does moving insurance cover broken furniture?
It may cover broken furniture when the damage happens during a covered service and no exclusion applies. The result depends on the valuation option, furniture condition, and agreement. Photograph the item before and after the move, keep packaging, and report damage promptly.
Are items in storage protected after a move?
Storage protection depends on the agreement and selected policy. Some protection may end after delivery, while another arrangement may cover goods during a stated storage period. Ask who is responsible during storage, what exclusions apply, and whether separate protection is needed.
Does moving insurance cover boxes packed by the owner?
Owner-packed boxes may have limited protection or may be excluded from some claims. This rule exists because the mover did not see how the contents were wrapped and placed. Ask about self-packed boxes before moving day and keep photos of fragile items before sealing each carton.
What should a customer do when an item is missing?
Compare the delivery inventory with the items that arrived. Describe the missing item in writing, along with its last known location and identifying details. Contact the mover through the stated claim process and keep copies of all records and messages.
Is full-value protection the same as replacement-cost coverage?
Not always. Full-value protection is a valuation option with its own rules, while replacement-cost coverage may appear in a separate policy. A mover may repair, replace, or pay for eligible items based on the agreement. Review the exact terms instead of relying on the label alone.
Conclusion
Moving insurance can help protect customers from certain loss or damage, but the details matter. Valuation options, full-value protection, owner-packed boxes, high-value goods, storage, and claim deadlines all deserve attention before the truck arrives.
Keep records, ask direct questions, and match protection with the shipment. Customers planning a move in Youngstown can use these steps to avoid confusion. Youngstown Movers helps customers plan moving services with a clear understanding of the work to be completed. Contact us to discuss the moving help and protection questions that apply to your move.